How Much Housing Benefit Am I Entitled to for Private Renting in 2027? Updated UK and London Guide
Housing Benefit entitlement for private renting in 2027 depends on income, savings, household size and local rent limits, with LHA rates remaining frozen.
 Adam
London Business & News Writer
If you rent privately in London or elsewhere in the UK, you may qualify for financial help towards your rent. However, how much Housing Benefit you are entitled to for private renting depends on your income, age, savings, household circumstances and Local Housing Allowance (LHA) rate.
The major 2027 update is that Local Housing Allowance rates will remain frozen for another year. On 28 October 2026, the government confirmed that LHA rates and the benefit cap would not increase during the 2027/28 financial year.
This follows the decision to maintain 2026/27 LHA rates at their April 2024 levels.
For renters, the implications are significant. If private rents continue rising while housing support remains unchanged, households may have to cover a greater proportion of their rent from wages, pensions, savings or other benefits.
Our analysis of the published benefit regulations, official London LHA figures and hypothetical private-renting budgets demonstrates that the proportion of rent potentially covered can range from less than 45% to 100%, depending on the household.
There is also an important eligibility distinction. Most working-age private renters now receive help through Universal Credit rather than a separate Housing Benefit payment.
Understanding that difference is essential before estimating how much support you might receive in 2027.
How Much Housing Benefit Can You Get for Private Renting in 2027?
There is no fixed Housing Benefit payment available to every private tenant.
For most ordinary private tenancies, the starting amount of rent recognised for Housing Benefit or Universal Credit is generally the lower of:
- The property’s actual eligible rent.
- The Local Housing Allowance rate for the household’s location and bedroom entitlement.
For example, if your landlord charges £1,500 per month and your relevant LHA rate is £1,200, the maximum rent normally recognised for support would be £1,200.
You would have an immediate £300 monthly difference between your contractual rent and the LHA ceiling.
However, this does not guarantee that you will receive £1,200. Your actual benefit award could be reduced because of earnings, capital, non-dependants or other applicable rules.
How Much Rent Can Housing Support Recognise?
The following table assumes a hypothetical £1,200 monthly LHA ceiling and no other restrictions.
| Monthly private rent | Maximum recognised housing amount | Potential rent coverage | Monthly LHA shortfall |
| £800 | £800 | 100% | £0 |
| £1,000 | £1,000 | 100% | £0 |
| £1,200 | £1,200 | 100% | £0 |
| £1,400 | £1,200 | 85.7% | £200 |
| £1,600 | £1,200 | 75% | £400 |
| £1,800 | £1,200 | 66.7% | £600 |
| £2,000 | £1,200 | 60% | £800 |
These percentages describe the proportion of rent that could be recognised before means-testing and other deductions. They are not guaranteed payment percentages.
From a household-finance perspective, the important figure is often the monthly shortfall rather than the headline allowance.
A £400 shortfall costs £4,800 over 12 months. At £800 per month, that increases to £9,600 annually.
Anyone comparing properties should therefore calculate how much rent they can realistically afford using their complete household income and expenditure, rather than relying exclusively on the maximum housing allowance.
What Are the Confirmed Housing Benefit Changes for 2027?
The government’s October 2026 announcement provides important clarity for people planning their finances for the following year.
Work and Pensions Secretary Pat McFadden confirmed in a written parliamentary statement dated 28 October 2026:
“Local Housing Allowance rates and the benefit cap will be maintained at their current levels and not increased for 2027-28.”
This is a confirmed policy announcement, rather than a forecast about future housing assistance.
Housing Benefit and Universal Credit Changes at a Glance
| Benefit or policy | Position in 2026/27 | Confirmed 2027/28 position |
| Local Housing Allowance | Frozen at April 2024 cash rates | Remains frozen |
| Benefit cap | Existing limits maintained | Remains frozen |
| Universal Credit standard allowance | 2026/27 rates apply | Further increases confirmed |
| Most benefits covered by annual uprating | 2026/27 rates apply | Increase by 3.5% |
| Basic and new State Pension | 2026/27 rates apply | Increase by 3.9% |
| Pension Credit Standard Minimum Guarantee | 2026/27 rates apply | Increase by 3.9% |
| England’s Housing Payment scheme | Introduced in April 2026 | Continues under the existing multi-year funding framework |
Most of the 2027 benefit uprating changes are scheduled to take effect from 12 April 2027.
The difference between the benefit uprating and the LHA freeze is particularly important.
A claimant may receive an increased Universal Credit standard allowance in 2027 while the maximum private rent recognised through the housing element remains unchanged.
Similarly, an eligible pensioner may see their State Pension increase without receiving a corresponding increase in their LHA ceiling.
Why the Freeze Matters to Private Renters?
Consider someone whose monthly rent increases from £1,400 to £1,500 while their applicable LHA ceiling remains £1,100.
Before the increase:
- Monthly rent: £1,400
- LHA ceiling: £1,100
- Rent potentially recognised: 78.6%
- Monthly shortfall: £300
After the increase:
- Monthly rent: £1,500
- LHA ceiling: £1,100
- Rent potentially recognised: 73.3%
- Monthly shortfall: £400
The tenant’s annual LHA-related shortfall rises from £3,600 to £4,800.
This is a 33.3% increase in the shortfall, despite the contractual rent rising by only 7.1%.
Our assessment is that the widening difference between rental costs and housing support is one of the most important affordability risks for private tenants entering 2027.
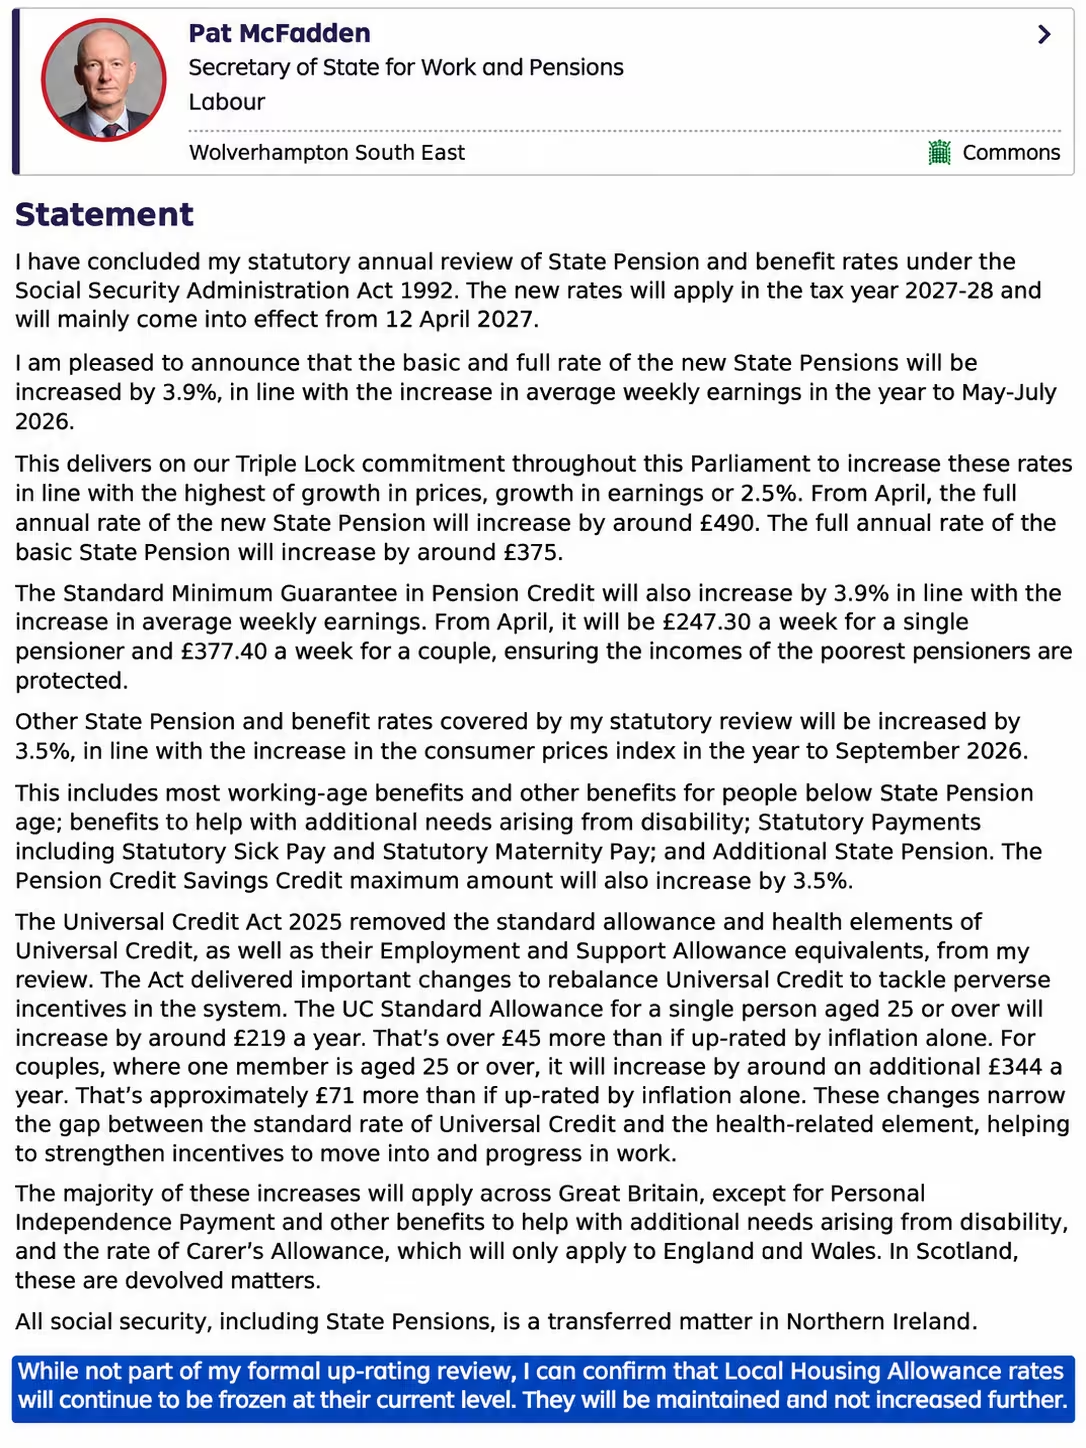
Government confirmation dated 28 October 2026 that Local Housing Allowance rates and the benefit cap will remain frozen in 2027/28.
Can You Still Claim Housing Benefit as a Private Tenant in 2027?
Yes, but a separate Housing Benefit claim is no longer available to most working-age people living in ordinary privately rented accommodation.
A major change took effect on 1 July 2026, when the government abolished most remaining working-age Housing Benefit awards for people outside qualifying temporary or specified accommodation, subject to limited exceptions.
Consequently, Universal Credit is now the principal route for most working-age private renters requiring financial assistance.
| Claimant circumstances | Main route for housing assistance |
| Working-age person renting privately | Universal Credit housing costs |
| Working-age couple in an ordinary private tenancy | Usually Universal Credit |
| Single person who has reached State Pension age | Housing Benefit, subject to eligibility |
| Couple where both partners are State Pension age | Normally Housing Benefit |
| Mixed-age couple | Normally Universal Credit unless protected rules apply |
| Qualifying temporary accommodation resident | Housing Benefit may apply |
| Qualifying specified supported accommodation resident | Housing Benefit may apply |
Some protected cases can continue under exceptions to the July 2026 closure regulations.
The distinction matters when searching online because older advice may still encourage ordinary working-age private tenants to apply to their local council for Housing Benefit.
For most such claimants, the appropriate application is now Universal Credit.
Our separate calculation of how much Universal Credit can pay towards private rent explains how its housing element fits into an overall monthly award.
What Are the Local Housing Allowance Rates in London for 2027?
London’s Local Housing Allowance is divided into Broad Rental Market Areas, commonly called BRMAs.
These rental market areas do not always correspond directly to London borough boundaries.
The rate is determined primarily by the property’s location and the number of bedrooms the household is entitled to under benefit rules.
The government has confirmed that 2027/28 rates will remain at their existing cash levels. However, the separate official 2027/28 area-by-area publication had not yet appeared in the government’s LHA collection as of 5 November 2026.
The following table therefore uses the officially published 2026/27 monthly Universal Credit LHA figures, which represent the rates being carried forward under the confirmed freeze.
London Local Housing Allowance Monthly Rates
| London rental market area | Shared rate | 1 bedroom | 2 bedrooms | 3 bedrooms | 4 bedrooms |
| Central London | £829.83 | £1,439.97 | £1,793.98 | £2,160.02 | £3,060 |
| Inner East London | £699.50 | £1,439.97 | £1,750 | £2,160.02 | £3,000 |
| Inner South East London | £650 | £1,295.50 | £1,550 | £1,950 | £2,625 |
| Outer West London | £576.33 | £1,000 | £1,300 | £1,475 | £1,800 |
| Outer South London | £569.33 | £950 | £1,200 | £1,500 | £1,950 |
These are published monthly Universal Credit LHA figures, not guaranteed individual benefit awards. Housing Benefit is generally calculated using weekly rates, and payment-period conversions and rounding can differ.
The highest applicable LHA category is normally four bedrooms, even where a larger household requires additional bedrooms.
Why Does the Same Property Size Have Different Allowances?
Consider a single renter aged 40 who qualifies for the one-bedroom rate.
In Central London, the published monthly allowance is £1,439.97.
In Outer South London, the equivalent figure is £950.
That is a difference of £489.97 per month, or £5,879.64 annually.
Both individuals may have identical incomes and rent similarly sized properties, yet the amount of rent recognised for assistance can differ substantially because of location.
This is why checking your specific postcode is more reliable than searching for a single London-wide Housing Benefit figure.
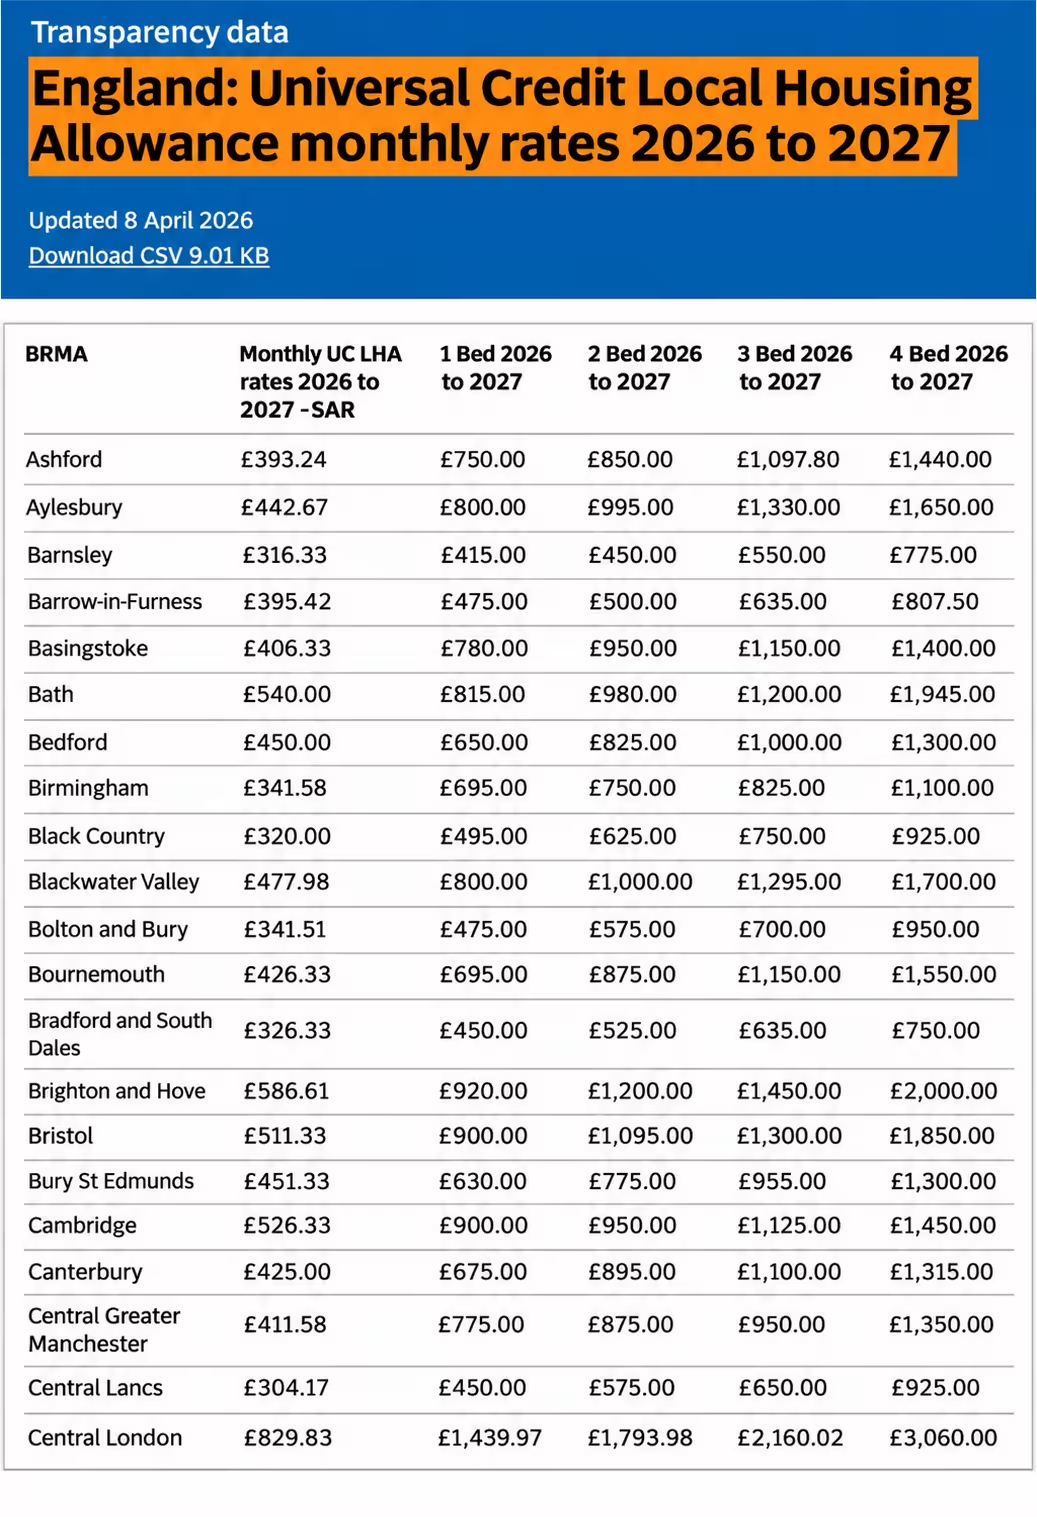
Official 2026/27 monthly Local Housing Allowance rates showing the different rent-support limits across London.
How Much of Your Private Rent Could Be Covered in London?
To demonstrate the financial effect of the LHA system, we calculated six illustrative renting scenarios using the published London monthly rates.
The figures assume that the household qualifies for the stated bedroom category and show the LHA ceiling before income-related or other deductions.
| Renting scenario | Monthly rent | LHA ceiling | Potential coverage | Monthly gap |
| Single aged 35+, Central London, 1 bedroom | £1,800 | £1,439.97 | 80% | £360.03 |
| Family qualifying for 2 bedrooms, Inner East London | £2,150 | £1,750 | 81.4% | £400 |
| Single under 35, Outer West London, shared rate | £1,350 | £576.33 | 42.7% | £773.67 |
| Single aged 35+, Outer South London, 1 bedroom | £1,250 | £950 | 76% | £300 |
| Household qualifying for 2 bedrooms, Outer West London | £1,300 | £1,300 | 100% | £0 |
| Family qualifying for 4 bedrooms, Central London | £3,800 | £3,060 | 80.5% | £740 |
These are calculated rent-coverage percentages, not subjective ratings or promises of entitlement.
Several findings stand out.
First, an eligible housing amount covering 80% of rent can still leave a substantial monthly liability.
Second, someone under 35 without an exemption from the shared accommodation restriction can face a particularly large shortfall.
Third, a household whose rent is at or below the relevant LHA rate may have 100% of its rent recognised, but only if the other conditions are satisfied.
Finally, a high four-bedroom rate does not automatically mean the family will receive that amount. Earnings, capital, the benefit cap and other deductions still matter.
How Many Bedrooms Are You Entitled to Under Housing Benefit Rules?
Your LHA bedroom entitlement is determined by household composition rather than simply the number of rooms in the property.
The normal rules allow one bedroom for:
- An adult couple.
- Each other person aged 16 or over.
- Two children of the same sex under 16.
- Two children under 10, regardless of sex.
- Any other child who cannot be expected to share under the normal rules.
Additional bedroom entitlement may apply in certain circumstances involving disability, overnight carers or qualifying foster carers.
Example: Single Parent With Two Young Children
A single parent has two children aged five and eight.
The parent would normally qualify for one bedroom, while the two children could share another bedroom.
The household would therefore generally be assessed using the two-bedroom LHA rate.
Example: Couple With Two Older Children
A couple has a 14-year-old daughter and an 11-year-old son.
Under the normal sharing rules, the children would not be expected to share a bedroom.
The couple would generally qualify for a three-bedroom rate.
However, choosing to rent a larger property does not automatically increase LHA entitlement.
A family qualifying for two bedrooms but renting a three-bedroom house would normally remain subject to the two-bedroom LHA ceiling.
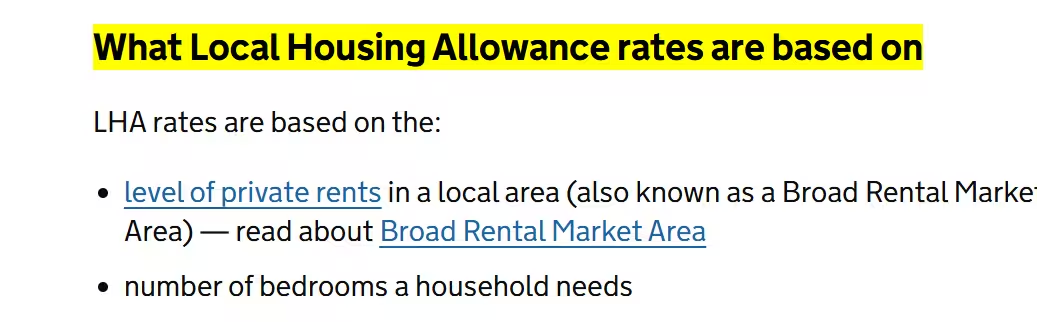
Official Local Housing Allowance information explaining how bedroom entitlement and property location affect rental assistance.
Why Do Single Private Renters Under 35 Receive Less Housing Support?
Single private renters under 35 who do not live with a partner or dependent children are generally restricted to the Shared Accommodation Rate.
This can apply even when they rent a self-contained one-bedroom flat.
For example, consider two people renting similar £1,350-per-month properties in Outer West London.
| Renter | Relevant monthly rate | Potential rent coverage |
| Single person aged 28, no exemption | £576.33 | 42.7% |
| Single person aged 38 | £1,000 | 74.1% |
The difference between the recognised rent amounts is £423.67 each month.
Over a year, that is £5,084.04.
Exceptions to the Shared Accommodation Rate
Some people under 35 can qualify for a higher rate.
Exceptions include certain claimants who:
- Receive the daily living component of Personal Independence Payment.
- Receive qualifying Disability Living Allowance or Attendance Allowance.
- Are care leavers under 25.
- Have previously spent at least three months in qualifying homeless hostel accommodation.
- Are subject to qualifying Multi-Agency Public Protection Arrangements.
- Are victims of domestic abuse.
- Are victims of modern slavery.
The precise conditions depend on the applicable benefit and exemption.
A private renter who may qualify for one of these exceptions should check the decision before assuming that the shared rate is correct.
Does Your Income or Salary Affect Housing Benefit in 2027?
Yes. Earnings can reduce the amount of means-tested housing assistance you receive.
However, the method differs between Housing Benefit and Universal Credit.
For remaining qualifying Housing Benefit claims, the council generally compares assessable income with an applicable amount reflecting household needs.
Where assessable income exceeds that amount, Housing Benefit is ordinarily reduced by 65% of the excess, subject to relevant disregards and other conditions.
Universal Credit uses a different system.
For most employed Universal Credit claimants, the award is reduced by 55p for each additional £1 of earnings taken into account above any applicable work allowance.
The 55% deduction applies to the overall Universal Credit award, rather than separately reducing only the housing element.
Example: Working Private Renter Receiving Universal Credit
Consider a single claimant aged over 25 in 2026/27 with:
| Financial item | Monthly amount |
| Universal Credit standard allowance | £424.90 |
| Eligible housing costs | £1,000 |
| Maximum UC before deductions | £1,424.90 |
| Net earnings taken into account | £1,200 |
| Earnings deduction at 55% | £660 |
| Illustrative UC payment | £764.90 |
This simplified example assumes the claimant has no work allowance, other elements, relevant unearned income or other deductions.
It demonstrates why a person can qualify for a £1,000 housing-cost element without receiving a separate £1,000 payment specifically earmarked for rent.
The Universal Credit award is calculated as a whole.
For 2026/27, the standard monthly allowance for a single claimant aged 25 or over is £424.90. The government has confirmed an above-inflation increase for 2027/28, equivalent to approximately £219 more annually for this claimant category.
The new standard allowance does not mean the LHA housing ceiling is increasing.
How Much Savings Can You Have and Still Receive Housing Benefit?
Savings, investments and other countable capital can affect eligibility.
For Universal Credit, the general rules in 2026/27 are:
| Countable savings | General treatment |
| £0–£6,000 | Normally ignored |
| More than £6,000 but not more than £16,000 | Assumed income reduces the award |
| More than £16,000 | Normally prevents entitlement, subject to exceptions |
For Universal Credit, capital above £6,000 generally creates a reduction of £4.35 per month for every £250, or part of £250, above the threshold.
For example, a claimant with £10,000 in countable savings has £4,000 above the disregard.
That is 16 complete £250 amounts.
The assumed monthly income deduction is:
16 × £4.35 = £69.60
The claimant’s Universal Credit award would ordinarily be reduced by £69.60 per month because of those savings.
Pension-age Housing Benefit generally has a higher initial capital disregard of £10,000.
Above this threshold, assumed income is normally calculated at £1 per week for every £500, or part of £500, of countable capital.
The £16,000 upper capital limit generally applies to Housing Benefit too, although claimants receiving Pension Credit Guarantee Credit benefit from an important exception.
Other capital disregards and transitional protections can apply.
Our financial assessment is that tenants should check their savings position before relying on a maximum LHA figure, particularly when a household is close to the relevant capital threshold.
Can Pensioners Get Their Full Private Rent Paid Through Housing Benefit?
Yes, qualifying pension-age renters can potentially receive assistance covering all their eligible private rent.
However, the amount depends on the LHA ceiling, household income, countable savings and any relevant deductions.
Someone receiving the Guarantee Credit element of Pension Credit will generally qualify for maximum Housing Benefit against their eligible rent, subject to applicable restrictions.
This does not mean the whole contractual rent will necessarily be covered if it exceeds the LHA ceiling.
For example, a single pensioner paying £1,700 per month in Central London may have a one-bedroom monthly LHA benchmark of £1,439.97.
That represents approximately 84.7% of contractual rent.
The difference is £260.03 per month before considering the Housing Benefit assessment and the applicable weekly payment calculation.
What Changes for Pensioners in April 2027?
The government has confirmed that the basic and new State Pensions will increase by 3.9% in 2027/28.
The Pension Credit Standard Minimum Guarantee will also increase by 3.9%, reaching:
| Household | Weekly guarantee from April 2027 |
| Single pensioner | £247.30 |
| Couple | £377.40 |
These are Pension Credit income-guarantee figures, not Housing Benefit payment rates.
A higher State Pension may affect the means-tested calculation for someone not receiving Guarantee Credit. Pension Credit eligibility and Housing Benefit should therefore be reviewed together.
Pension-age Housing Benefit claimants are also generally outside the benefit cap.
Can the Benefit Cap Reduce Your Rent Support in 2027?
Yes. Some working-age households are subject to a limit on the total benefits they can receive.
The government confirmed on 28 October 2026 that this cap would also remain frozen in 2027/28.
The current monthly limits are:
| Household type | Greater London | Outside Greater London |
| Couple, with or without children | £2,110.25 | £1,835 |
| Single parent with dependent children | £2,110.25 | £1,835 |
| Single adult without children | £1,413.92 | £1,229.42 |
These amounts apply to the total benefits included in the cap calculation, not solely to rent.
Certain disability-related benefits, caring circumstances and other exemptions can remove the cap.
For Universal Credit, qualifying combined household earnings of at least £881 per monthly assessment period after tax and National Insurance can provide an exemption under the 2026/27 rules.
A qualifying nine-month grace period may also apply following a reduction in earnings or the loss of employment.
For larger private-renting households, the benefit cap can be particularly important. A four-bedroom LHA ceiling of £3,060 in Central London does not mean an affected family will necessarily receive £3,060 in housing support.
Can Other Adults Living in Your Home Reduce Housing Benefit?
Potentially.
An adult who lives with you but is not your partner may be treated as a non-dependant for benefit purposes.
For qualifying Housing Benefit claims, non-dependant deductions depend on circumstances, with different weekly rates for different earnings bands.
Under Universal Credit, a standard housing-cost contribution may apply to relevant adults aged 21 or over.
The standard 2026/27 Universal Credit housing-cost contribution is £96.55 per month, subject to exceptions.
For example, if an adult son or daughter lives permanently in the property, the claimant may have a housing-cost deduction even if that person does not actually contribute towards the rent.
Exemptions can apply according to the person’s age, circumstances and relevant disability-related benefits.
This is one reason a household’s final benefit award can be lower than a simple online LHA estimate.
What Happens if Your Landlord Increases the Rent in 2027?
An increase in contractual rent does not automatically increase Housing Benefit or Universal Credit.
Where the rent is already above the applicable LHA ceiling, the tenant may have to fund the entire additional increase.
Consider a property where the LHA ceiling is £1,300.
| Financial position | Before increase | After increase |
| Monthly rent | £1,500 | £1,650 |
| LHA ceiling | £1,300 | £1,300 |
| Potential rent coverage | 86.7% | 78.8% |
| Monthly LHA shortfall | £200 | £350 |
| Annual LHA shortfall | £2,400 | £4,200 |
The rent increases by 10%, but the annual LHA shortfall rises by 75%.
This demonstrates why rent increases deserve particular attention while allowances are frozen.
England’s Renters’ Rights reforms, introduced in May 2026, also changed the procedure governing increases for most covered private assured tenancies.
Landlords normally need to use the statutory Section 13 process and provide at least two months’ notice. Increases are generally limited to once a year under this framework.
Tenants should understand how much a landlord can increase rent before accepting or challenging a proposed increase.
The tenant must also report relevant rent changes to the appropriate benefit authority.
Can Landlords Refuse Tenants Who Receive Housing Benefit?
A significant change introduced in England on 1 May 2026 prohibits landlords and letting agents from discriminating against prospective renters simply because they receive benefits or have children, subject to limited statutory exceptions.
The protections cover people receiving Housing Benefit, Universal Credit and other relevant benefits.
Landlords cannot generally reject someone solely because their income includes benefit payments.
However, they can still carry out lawful, proportionate affordability assessments.
That distinction matters for tenants whose benefits cover a substantial part of their housing costs.
A tenant receiving housing assistance still needs to demonstrate that the overall contractual rent can be met.
The landlord’s responsibilities, tenancy conditions and compliance obligations are also important parts of the private letting process.
For tenants, the practical lesson is that benefit status alone should not prevent an application, but the property’s affordability still requires careful assessment.
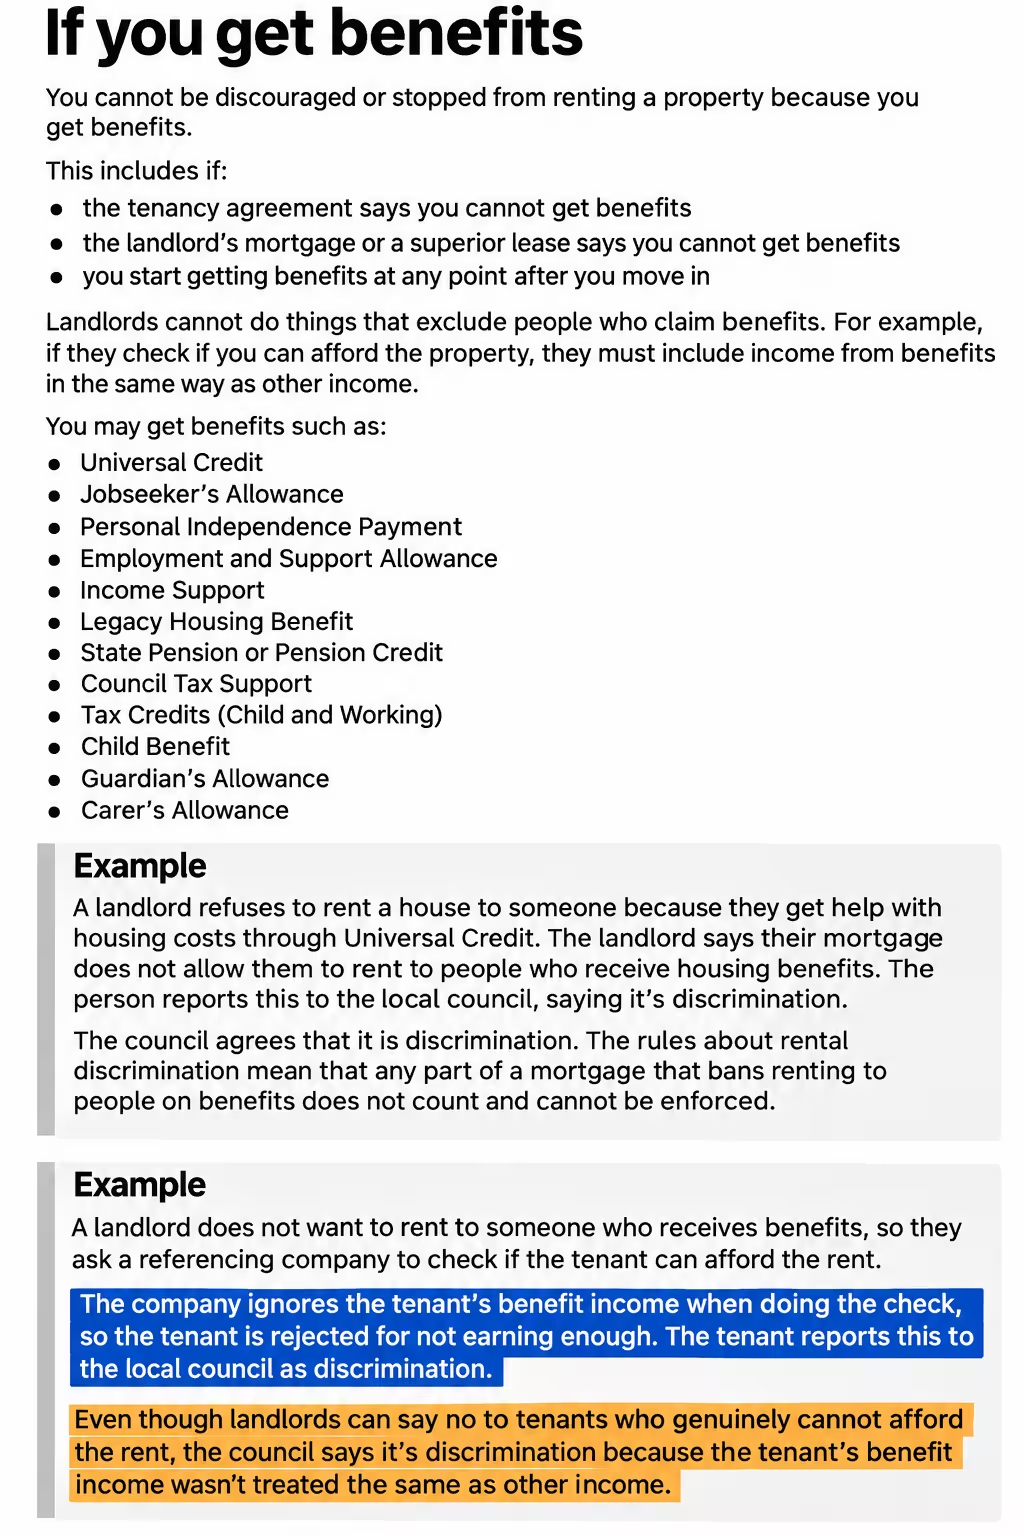
Official government guidance confirming protections against rental discrimination for tenants receiving benefits.
What Extra Help Is Available if Housing Benefit Does Not Cover Your Rent?
If your Housing Benefit or Universal Credit housing element is insufficient, additional support may be available through your local authority.
In England, a major change occurred on 1 April 2026.
Discretionary Housing Payments ended on 31 March 2026 and were replaced by Housing Payments under the Crisis and Resilience Fund.
This support can assist qualifying households experiencing financial difficulties with housing costs.
Depending on the local authority’s assessment, Housing Payments may help with:
- Shortfalls between housing assistance and actual rent.
- Rent deposits.
- Rent in advance.
- Certain costs involved in securing suitable accommodation.
- Qualifying removal or moving expenses.
- Other eligible housing-related pressures.
Housing Payments are discretionary. They are not a guaranteed entitlement or an automatic permanent increase in Housing Benefit.
The Crisis and Resilience Fund operates under a multi-year framework running from April 2026 to March 2029.
Housing Payment allocations continue within that framework during 2027/28.
Scotland and Wales continue to have separate Discretionary Housing Payment arrangements.
How to Apply for Additional Housing Assistance?
Private renters in England should contact their local council and ask about its Crisis and Resilience Fund Housing Payment scheme.
The council may request:
- A current tenancy agreement and rent details.
- A Housing Benefit award notice or Universal Credit statement.
- Bank statements and evidence of household income.
- Details of essential living costs and debts.
- Evidence of rent arrears, hardship or risk of homelessness.
- Information about disability, caring responsibilities or other relevant circumstances.
The council will assess the application according to the applicable scheme rules.
Where someone faces imminent eviction or homelessness, they should also contact the council’s homelessness team immediately rather than relying only on a discretionary payment application.
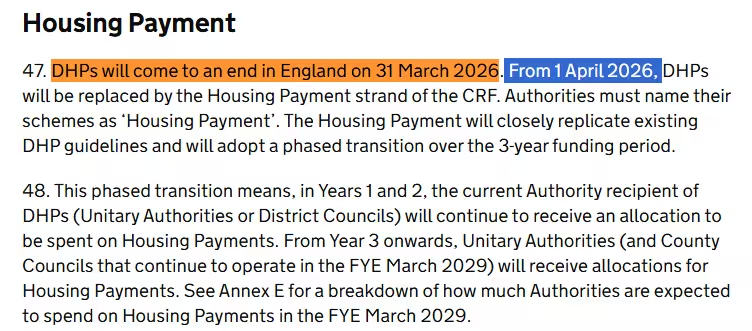
Government guidance showing how Housing Payments replaced Discretionary Housing Payments in England from April 2026.
How Can You Calculate Your Housing Benefit Entitlement Before Renting?
A reliable estimate should combine the correct benefit route, local rent limits and your complete financial position.
Our recommended calculation follows seven stages.
- Step 1: Identify the appropriate benefit: Establish whether you qualify for Housing Benefit or need to claim Universal Credit.
- Step 2: Find your LHA area: Enter the property’s postcode into the official Local Housing Allowance tool.
- Step 3: Determine bedroom entitlement: Include children, other adults, relationship circumstances and any qualifying disability or care-related exceptions.
- Step 4: Compare LHA with eligible rent: The lower amount normally establishes the starting rent figure recognised for assistance.
- Step 5: Assess household income and savings: Include earnings, pensions, capital, relevant other benefits and possible deductions.
- Step 6: Calculate the expected shortfall: Compare the actual contractual rent with the realistic amount of financial assistance.
- Step 7: Use a full benefits calculator: Check the wider entitlement rather than calculating only the housing element.
The official GOV.UK benefits calculator service directs people to independent calculators that can estimate entitlement.
Example: Calculating a Monthly London Renting Budget
Suppose a household pays £1,650 per month and its relevant LHA ceiling is £1,300.
| Monthly financial item | Amount |
| Private rent | £1,650 |
| LHA ceiling | £1,300 |
| Maximum rent potentially recognised | £1,300 |
| LHA-related monthly gap | £350 |
| LHA-related annual gap | £4,200 |
| Potential recognised rent coverage | 78.8% |
This is the starting affordability calculation, not a final benefit assessment.
If household income or other rules reduce the actual benefit award, the financial pressure could be greater.
When comparing a property’s advertised rent, tenants should also distinguish between weekly rent and the amount expressed per calendar month.
For example, £350 per week is approximately £1,516.67 per calendar month when calculated over 52 weeks.
Multiplying the weekly amount by four would understate the equivalent monthly cost.
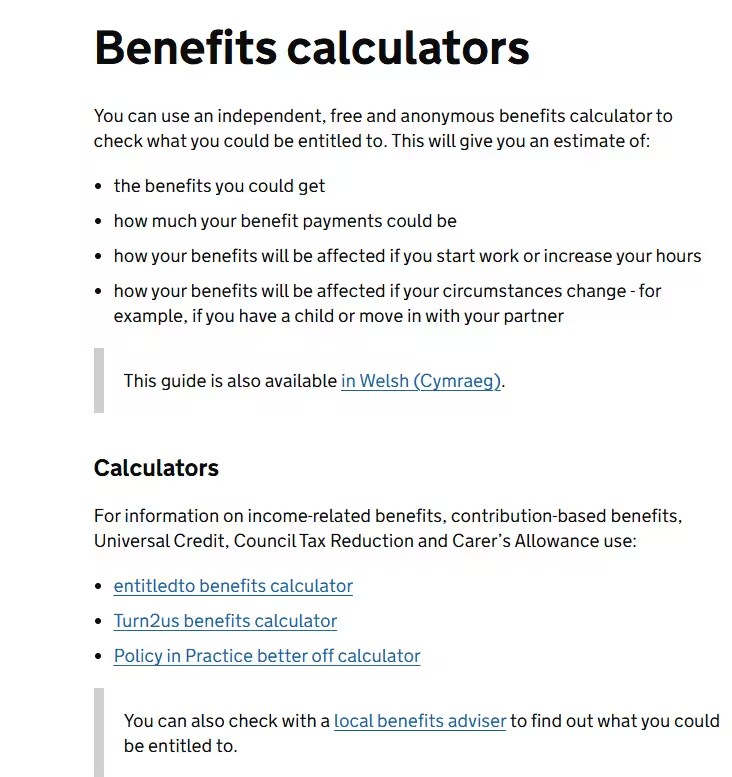
Official government information showing where to find free benefits calculators for Housing Benefit and Universal Credit.
How Do You Apply for Housing Benefit or Universal Credit in 2027?
The application process depends on your circumstances.
For Working-Age Private Renters
Most working-age people should apply through Universal Credit.
The process generally involves creating or accessing a Universal Credit account, reporting accommodation details and providing evidence of rental liability.
Applicants may need to provide their tenancy agreement, address, landlord details and rent information.
Universal Credit housing costs are usually included in the overall monthly payment, and the tenant normally pays their landlord.
Alternative arrangements, including a managed payment to the landlord, may be available in qualifying circumstances.
For Pension-Age Housing Benefit Claimants
Qualifying pension-age applicants can apply through their local council or, where eligible, as part of a Pension Credit claim.
The council may require evidence of:
- Identity and National Insurance details.
- Tenancy and rent liability.
- Income and pension payments.
- Savings and other capital.
- Household composition.
- Relevant disability or care-related circumstances.
Applicants may be able to claim Housing Benefit in advance of a move within the applicable time limits.
Backdating can also be possible, subject to the relevant rules and circumstances.
People whose formal Housing Benefit assessment appears incorrect can ask the council to review its decision and, where appropriate, appeal.
Before starting a new tenancy, renters should also understand the steps involved in renting a home, including deposits, references and contractual obligations.
For some tenants in England, a Right to Rent share code may also be relevant to immigration-status verification, although Right to Rent checks and benefit entitlement are separate legal requirements.
What Should Private Renters Check Before 2027?
Our review of the confirmed 2026 rules and 2027 announcements identifies several financial risks worth assessing before entering or renewing a tenancy.
The first is the continuing LHA freeze. Tenants should avoid assuming that their housing allowance will automatically increase when their landlord raises the rent.
The second is the difference between eligible housing costs and actual benefit entitlement. A household may qualify for a relatively high LHA rate without receiving the full amount because of income, savings or other restrictions.
The third is the importance of longer-term affordability.
A property with a £300 monthly shortfall requires £3,600 annually from other household resources. A £700 monthly shortfall requires £8,400.
Even a modest change in rent, employment income or household circumstances can make a substantial difference.
For people facing uncertainty about their benefit amount, the most useful starting point is to check the applicable rules and how much Housing Benefit can be awarded, then use an up-to-date benefits calculator and obtain confirmation from the relevant authority.
The financial decision should be based on realistic disposable income after rent, bills, Council Tax, transport, food and other necessary commitments.
Conclusion
How much Housing Benefit you are entitled to for private renting in 2027 depends on your circumstances rather than a fixed national payment.
Most working-age renters receive housing assistance through Universal Credit, while qualifying pension-age tenants and certain accommodation residents can still receive Housing Benefit.
The government’s confirmed freeze on Local Housing Allowance rates and the benefit cap for 2027/28 means private tenants cannot rely on higher rent-support limits to offset rising housing costs.
Our calculations demonstrate why checking the correct LHA rate, income deductions and monthly rent shortfall is essential. Before agreeing to a tenancy, obtain a realistic benefit estimate and calculate whether the remaining rent is affordable.
Frequently Asked Questions
How much Housing Benefit can I get for private renting in 2027?
There is no standard amount. The starting figure is generally the lower of your eligible rent and applicable LHA rate, followed by assessments of income, savings and other circumstances.
Will Housing Benefit increase in April 2027?
The government has confirmed that Local Housing Allowance rates will remain frozen for 2027/28. Although several other benefits will increase, private rent-support ceilings will not receive a general uplift.
Can Housing Benefit pay £1,500 per month?
Potentially, where the applicable rent limit and the claimant’s circumstances permit that amount. However, an LHA ceiling of £1,500 does not automatically mean a claimant will receive £1,500.
Can I claim Housing Benefit if I am working?
Employment does not automatically prevent assistance. Most working-age private renters claim Universal Credit housing costs, and earnings can reduce their overall award.
How much Housing Benefit can a single person under 35 receive?
A single person under 35 without dependent children is normally restricted to the shared accommodation rate unless an exemption applies. The amount varies by local rental market area.
Will Housing Benefit cover my full private rent?
It can cover the full eligible rent if the relevant rent limit and means-tested assessment allow it. Where actual rent exceeds the applicable LHA ceiling, the household will normally need to cover the difference.
Can pensioners claim Housing Benefit in 2027?
Yes. Qualifying pension-age renters can still claim Housing Benefit, subject to the relevant eligibility, income, capital and household rules.
What if my landlord charges more than my Housing Benefit allowance?
You are generally responsible for the shortfall. In England, eligible households receiving housing assistance can also ask their local council about discretionary Housing Payments under the Crisis and Resilience Fund.
Adam is a London business and news writer at London Insider News, covering local developments, finance, entrepreneurship and the stories shaping businesses and communities across the capital.
More from RENTING
Right to Rent Share Code 2027: How to Get, Generate and Check Your Code Online?
Updated: 4 November 2026 | 2027 Guide A Right to Rent share code is a nine-character…
How Much Housing Benefit Can I Get in 2027? UK Rates, Eligibility, Rent Calculations and 2026 Updates
How much Housing Benefit can I get in 2027? You could receive financial assistance covering up…
How Much Can a Landlord Increase Rent in London? 2026 Rules Explained
For most private renters in London, there is no fixed legal percentage cap limiting a landlord…